Business
The Case Against Betting Everything on Private Equity
Investors are increasingly turning to private equity in search of opportunities beyond traditional public markets. Governments, too, are encouraging savers, pension funds, and other investors to put more capital into private equity and private credit. In the United States, policymakers have moved to expand the investment options available through retirement plans, including private assets. In Britain, 17 major workplace pension providers pledged under the Mansion House Accord to allocate at least 10% of their default funds to private markets by 2030. The shift reflects a growing conviction that public markets alone cannot meet every investor’s needs or finance every part of an economy.
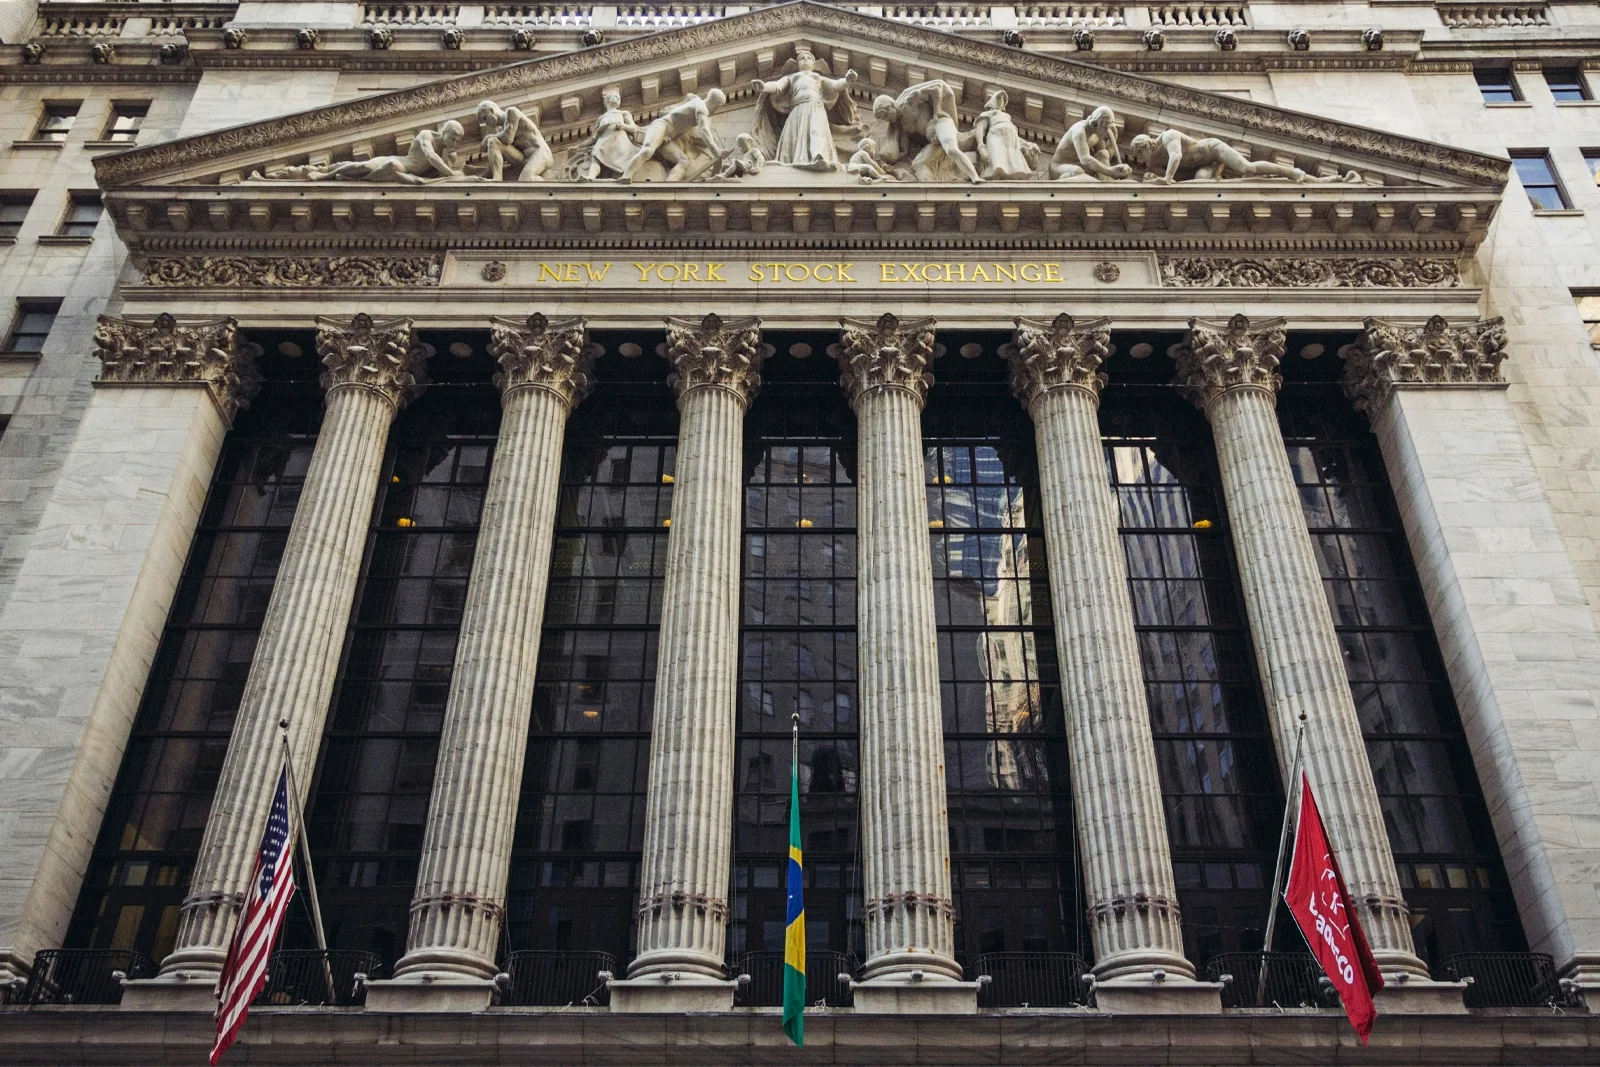
Yet moving capital out of listed markets does not eliminate risk. It changes where that risk sits, how easily it can be measured, and when investors may be forced to confront it. Public equities can react sharply to geopolitical shocks, from the wars involving Iran and Ukraine to fears that enthusiasm for artificial intelligence has pushed valuations beyond sustainable levels. Private investments may appear steadier because they are valued less frequently, but that apparent calm should not be mistaken for immunity from market turmoil.
Some of the most influential figures in finance have warned against confusing diversification with safety. JPMorgan Chase CEO Jamie Dimon has raised concerns about vulnerabilities in private credit, particularly following the collapses of Tricolor and First Brands. In Britain, Lord Jonathan Kestenbaum has emphasized the importance of matching investments to different risk appetites and time horizons. His experience spans public equities, including service on the board of Pershing Square Holdings, and a wider range of assets through RIT Capital Partners. Pershing Square’s concentrated, research-driven approach to listed stocks offers one model; RIT’s multi-asset strategy offers another. Neither is a universal answer.
BlackRock CEO Larry Fink has similarly questioned whether the familiar portfolio split of 60% stocks and 40% bonds provides sufficient diversification for today’s markets. The broader lesson is not that investors should abandon public equities, but that different kinds of capital serve different purposes. As Kestenbaum told the House of Lords Financial Services Regulation Committee, “flourishing economies thrive with multiple pools of capital that have different risk profiles, time horizons, and return profiles – a kind of ecosystem.” His work as chief operating officer of J. Rothschild Capital Management, the investment manager of RIT Capital Partners, illustrates that principle. RIT’s mandate has encompassed public stocks, private equity, venture capital, credit funds, and real assets.
For governments seeking growth, this ecosystem matters as much as it does for individual portfolios. Publicly traded companies operate under established disclosure requirements, and their shares can generally be bought or sold daily. That liquidity is valuable, although it also leaves prices exposed to rapid swings in sentiment. Private markets may provide longer-term financing for businesses and infrastructure that cannot easily access public exchanges. In return, investors typically accept less liquidity, less frequent valuations, and greater difficulty assessing what an asset is worth.
Pension funds are especially important to this debate because their long investment horizons can, in principle, support patient capital. But encouraging retirement savings to flow into private assets is not itself an economic-growth strategy. The underlying projects must be productive, their valuations credible, and their risks clearly disclosed. Governments that promote broader access also bear responsibility for ensuring that investors understand the trade-offs. A portfolio containing more asset classes is not necessarily a portfolio that is better protected.
The scale of the private-credit market underscores the stakes. The Financial Stability Board has estimated its size at roughly $1.5 trillion to $2 trillion, while access has expanded beyond the institutional investors who traditionally dominated the sector. Critics, including Dimon, have questioned how parts of this market would perform under severe stress. Public debt markets, meanwhile, remain an important source of long-term finance. Green-bond issuance has expanded, and Britain’s £6.25 billion green gilt announced in March 2026 illustrates how sovereign borrowing can support projects, including eligible energy investments.
These sources of finance can complement one another without being interchangeable. When listed shares fall on fears of an AI bubble or an oil shock, investors with genuinely long horizons may be able to hold private assets rather than sell at a loss. When private lenders pull back, public bond markets may still provide funding. But the capacity to withstand a shock depends on the financial health of lenders, borrowers, and investors, not simply on whether an asset is publicly or privately held.
The central question, then, is not whether private equity is superior to public markets. It is whether each pool of capital serves a useful purpose, with risks proportionate to the returns it promises and the time investors can afford to wait. Policymakers should resist declaring a winner. Their job is to preserve access, demand meaningful disclosure, and ensure that the pursuit of growth does not disguise illiquidity or obscure losses. An economy is more resilient when its sources of finance are diverse, transparent, and understood.