Business
Economic Diplomacy Needs More Than Billion-Dollar Deals
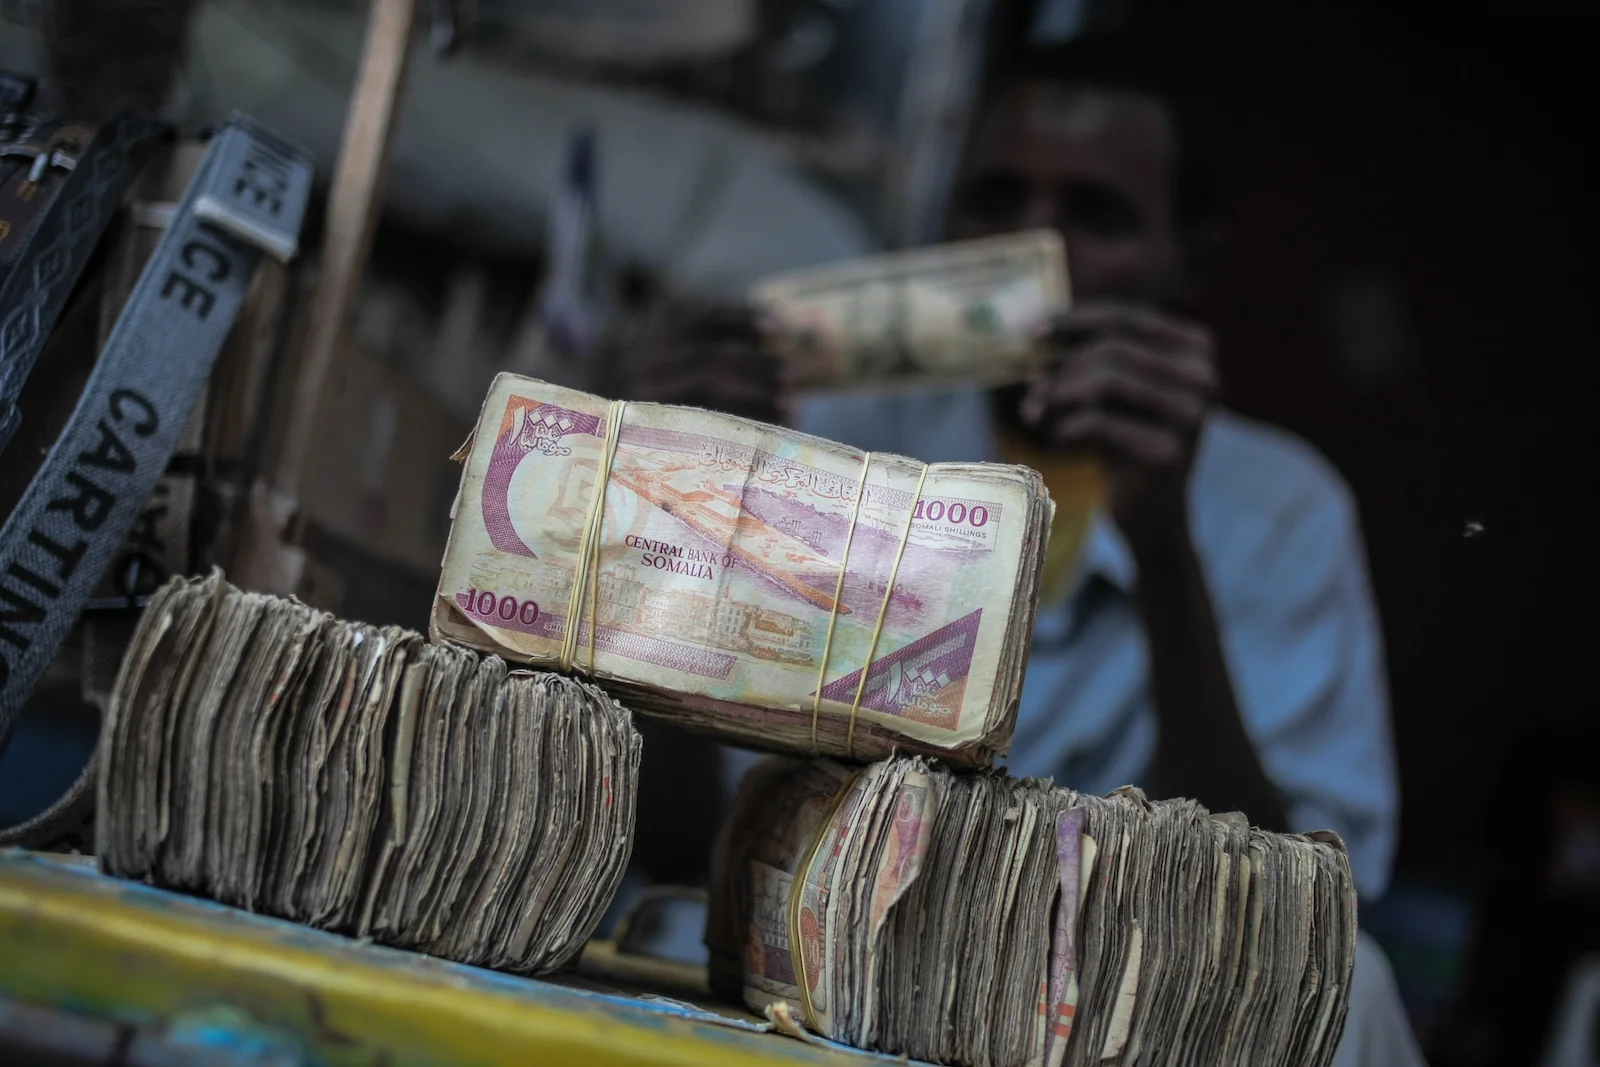
Economic diplomacy has a familiar vocabulary: billion-dollar trade agreements, investment corridors, sovereign wealth funds, and ambitious infrastructure projects. These are important measures of international cooperation. Yet they reveal remarkably little about whether a woman running a small business can secure affordable financing, whether a first-time borrower understands the terms of a contract, or whether a family can withstand an unexpected financial crisis.
That disconnect matters as governments promise more inclusive economic partnerships across the Gulf, India, and Europe. According to the Islamic Financial Services Board’s 2026 stability report, Islamic financial services held approximately $4.4 trillion in assets in 2025. Meanwhile, the World Bank’s Global Findex 2025 found that 1.3 billion adults worldwide still lacked a financial account.
The figures measure different things and should not be treated as directly comparable. Nevertheless, they illustrate a broader political challenge: a rapidly expanding financial system is not necessarily an inclusive one. Islamic finance offers principles that could help narrow that divide, provided its ethical promises are judged by measurable outcomes rather than accepted at face value.
Islamic finance is frequently reduced to its prohibition on interest, known as riba. But that overlooks much of its underlying philosophy. In principle, financial transactions should be tied to legitimate economic activity, excessive speculation should be discouraged, and financial relationships should recognize responsibilities beyond maximizing returns. The World Bank’s Global Islamic Finance Development Center emphasizes asset-backed financing, risk sharing, financial inclusion, and social welfare as defining principles.
Important distinctions exist within this framework. Mudaraba and musharaka involve profit-sharing or partnership arrangements, while murabaha is a cost-plus sale rather than an equity partnership. Zakat, an obligatory form of charitable giving for eligible Muslims, and waqf, a charitable endowment intended to provide enduring benefits, belong to Islamic social finance rather than conventional banking. Treating these mechanisms as interchangeable obscures their fundamentally different purposes, obligations, and risks.
What, then, can Islamic finance contribute to economic diplomacy? Certainly not a universal banking model, nor the assumption that religiously grounded financial institutions automatically produce fairer outcomes. Its potential lies in introducing different questions into international economic cooperation: Who bears the losses? Who benefits from investment? And who gets to decide which projects deserve financing?
The changing geography of international trade makes these questions particularly relevant. The UAE–India Comprehensive Economic Partnership Agreement entered into force in May 2022. The European Union and India concluded negotiations on a free-trade agreement in January 2026, although the agreement still requires the necessary approvals before taking effect. The EU has also expanded its diplomatic and economic engagement with the Gulf, including negotiations with the UAE on a strategic partnership.
These relationships are generally discussed in terms of logistics, investment flows, and market access. All are essential. Yet an infrastructure corridor that moves goods efficiently while leaving smaller suppliers behind represents an incomplete form of economic integration. Partnerships measured exclusively by aggregate trade figures can conceal how unevenly their benefits are distributed.
Neither India nor European countries need to adopt Islamic banking institutions wholesale. Their legal frameworks, religious traditions, and consumer expectations differ considerably. A more practical approach would examine which financial instruments, and which regulatory safeguards, could function across institutional boundaries. Gulf investors, Indian business networks, and European development institutions could learn from one another without pretending their financial systems are interchangeable.
This possibility is more than theoretical. A 2025 report jointly prepared by the Islamic Development Bank Institute and the United Nations Development Programme examined how Islamic microfinance and financial technology could reach underserved communities while preserving financial integrity and responding to local needs. In October 2026, UNDP discussions at AidEx Geneva explored combining commercial Islamic finance with zakat, waqf, guarantees, and other forms of catalytic capital.
The underlying logic is persuasive, provided these arrangements are designed responsibly. Grants can help vulnerable households meet immediate needs. Charitable endowments can finance training, education, or advisory services. Commercial financing can then support viable enterprises without requiring charitable resources to absorb every business risk. These mechanisms serve complementary purposes rather than offering interchangeable solutions.
The possibilities also extend well beyond the Gulf. In Indonesia, UNDP and national partners launched a Green Zakat Framework in 2025, seeking to connect Islamic philanthropy with climate resilience and poverty reduction. Its importance lies in the institutional experiment itself, not in any premature assumption that the initiative has already demonstrated measurable success.
Still, the language of ethical finance can conceal uncomfortable realities. A financial product may satisfy formal religious requirements while reproducing the same inequalities found in conventional banking. The IFSB’s 2026 report raises concerns about hybrid financial structures whose underlying economic risks increasingly resemble those associated with conventional credit products. Compliance with religious or contractual requirements does not automatically translate into meaningful risk sharing or adequate consumer protection.
Nor does opening a bank account necessarily constitute economic empowerment. The World Bank’s research on gender and digital finance identifies restrictive product design, inadequate agent networks, transaction costs, and institutional biases as obstacles to women’s effective participation. Financial inclusion becomes meaningful when individuals can understand financial obligations, make independent decisions, save securely, and strengthen their capacity to earn a living.
An inclusive approach to economic diplomacy therefore requires clear and enforceable benchmarks. Financial contracts should explain total costs, dispute procedures, and the allocation of losses in language borrowers can understand. Programs should measure whether women and smaller enterprises actually use financial services, rather than simply counting those theoretically eligible. Publicly supported initiatives should assess business survival, productive investment, and consumer complaints alongside the volume of financing disbursed. Independent oversight and proportionate consumer protections are especially important when charitable and commercial funding intersect.
These expectations should apply equally to conventional finance. The argument is not that one religious or financial tradition has discovered a solution to economic exclusion. Rather, the ethical principles associated with Islamic finance offer a useful standard against which the shortcomings of all financial systems can be examined.
International economic diplomacy will always depend on investment, trade agreements, and infrastructure. But it also requires institutions capable of translating ambitious international commitments into opportunities that ordinary people can actually use. Islamic commercial and social finance could contribute meaningfully to that effort, provided transparency, independent governance, and measurable participation become central to their implementation.
The next milestone in economic cooperation between the Gulf, India, and Europe should not be another carefully staged photograph of leaders signing a memorandum. It should be demonstrable evidence that their partnerships have enabled more people to start businesses, withstand financial setbacks, and participate in economic life.
Only then will inclusion become something more than another fashionable adjective in the language of diplomacy.